Hit by an Uninsured Driver in Arizona? How Your Car Repair Gets Paid
The short answer: If an uninsured driver damages your car in Arizona, the repair is usually paid by your own collision coverage, minus your deductible. Arizona’s uninsured motorist law is written for bodily injury, not for damage to your vehicle, so uninsured motorist coverage usually helps with medical costs, not the body shop bill. If you don’t carry collision coverage, your options are to claim against the other driver directly or pay for the repair yourself.
Below, we explain why that is, what to do in the first hour, how the claim works with your own insurer, and what happens once your car reaches the shop.
Why this happens more than you’d think in Arizona
Arizona requires every driver to carry liability insurance, and Arizona is an at-fault state: the driver who causes the crash is responsible for the damage. Normally, the other driver’s liability policy pays to fix your car. When that driver has no insurance, there is no policy to send the bill to.
It isn’t rare. The Insurance Research Council estimates that 10.6% of Arizona drivers were uninsured in 2023, about one in ten, according to the Insurance Information Institute’s uninsured motorist data. Nationally the figure was 15.4%.
Even an insured driver may not have enough coverage. Under A.R.S. § 28-4009, the minimum property damage liability in Arizona is $15,000 per accident. A collision with a newer SUV or a car full of sensors can cost more than that to repair.
Who pays to fix your car: your options
Arizona law defines uninsured motorist coverage as coverage “for damages due to bodily injury or death” caused by an uninsured vehicle, under A.R.S. § 20-259.01. The statute does not extend it to damage to your car. That leaves these paths for the repair:
| Option | What it pays for | What to know |
|---|---|---|
| Your collision coverage | Repairs to your car, whoever was at fault | You pay your deductible. This is the most common way the repair gets paid. |
| A property-damage add-on, if your policy has one | Depends on your policy wording | Not standard in Arizona. Ask your insurer whether your policy includes anything like it before you assume it does. |
| A claim against the uninsured driver | Whatever you can recover from that person | They may not have the money to pay. You generally have two years to file a property damage lawsuit in Arizona under A.R.S. § 12-542. |
| Paying for the repair yourself | Whatever you choose to fix | Get a written estimate first so you know the full cost. |
Uninsured motorist coverage still matters if anyone in your car was hurt. Arizona insurers must offer it in writing, and it is easy to decline without noticing, so it is worth checking your declarations page.
If you’re not sure whether you carry collision coverage, our guide to what collision insurance covers explains how it works and what it leaves out.
What to do right after the crash
The first hour matters most, because you may be the only one gathering information.
- Get safe and check for injuries. Call 911 if anyone is hurt.
- Call the police. A police report records the crash and the other driver’s lack of insurance. Insurers commonly ask for the report number.
- Collect the other driver’s details. Name, phone number, address, driver’s license number, license plate and vehicle description, even if they say they have no insurance.
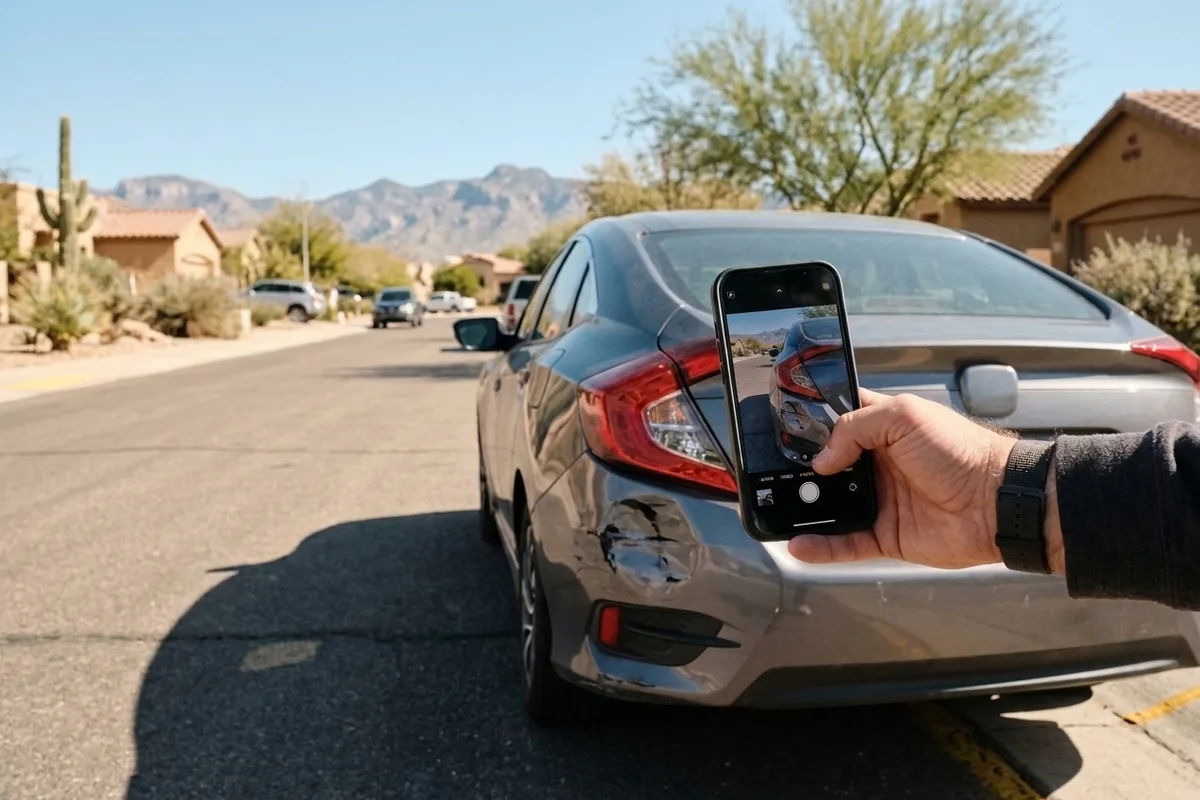
- Photograph everything. Damage to both cars, the plates, the scene, skid marks and the street signs or intersection.
- Get witness contacts. Independent witnesses help if fault is disputed later.
- Don’t agree to a cash deal at the curb. Damage is often bigger than it looks, and an informal promise is hard to collect on.
- Arrange a tow if the car isn’t safe to drive. See our towing assistance page for how that works.
Driving without insurance carries penalties in Arizona: a minimum $500 civil penalty and a three-month license suspension for a first violation, under A.R.S. § 28-4135. That is between the other driver and the state, though; it does not pay for your repair.
Filing the claim with your own insurance
Call your insurer as soon as you can and tell them the other driver was uninsured. Have the police report number, your photos and the other driver’s information ready.
- Expect to pay your deductible. Your collision coverage pays the repair cost above your deductible.
- Ask about recovery. After paying your claim, your insurer may try to recover its costs from the at-fault driver. Ask whether they will pursue it, and whether your deductible could be returned if they collect.
- Ask about a rental. Rental coverage is usually a separate part of the policy. Check whether you have it before the car goes in.
- You choose the shop. Arizona law gives you “the right to choose any repair facility” for a vehicle repair, under A.R.S. § 20-468, even if your insurer recommends one.
For the full claim process, from the first call to final approval, see our step-by-step guide to Arizona insurance claims.
What happens at the body shop
Once your car arrives, the repair follows the same process as any insurance claim. At Formula 1 Collision Center, that looks like this:
- Inspection and estimate. We analyze the damage and write a detailed estimate for you and your insurance company. An appointment isn’t required for an estimate, but it helps us serve you faster.
- Authorization first. We don’t start repairs until we have your authorization and your insurance carrier’s.
- Disassembly and supplements. Hidden damage often shows up once the damaged area is taken apart. If it is accident-related, we prepare a supplemental invoice and submit it to your insurer.
- Payment. If your insurer sent you a check, that payment and your deductible are paid to the shop when the repair is finished. We handle any additional charges directly with your carrier.
- Rental. We can arrange a rental car while your vehicle is in the shop and can often help with direct billing to your insurer.
The average collision repair takes four to five working days, and we can give you a better estimate after disassembly. Our repair workmanship is covered by a Lifetime Limited Warranty for as long as you own the vehicle.
For more about our process, see our page on collision repair in Tucson.
If you don’t have collision coverage
Without collision coverage, nothing in your own policy pays for the car, and the repair depends on what you can recover from the other driver.
- Get a written estimate now. It shows the full cost of the damage and supports a claim or a small claims case.
- Keep every document. The police report, photos, estimate, repair invoice and towing receipts.
- Ask for payment in writing. If the other driver agrees to pay, put the amount and the dates in writing.
- Talk to an attorney if it’s a large loss. Collecting from an uninsured person can be difficult, and this article is not legal advice.
After the repair, ask your agent what collision coverage would cost. It is the coverage that pays for your car when the other driver can’t.
Uninsured driver FAQ
Does uninsured motorist coverage pay for my car in Arizona?
Usually not. Arizona’s statute defines uninsured motorist coverage as coverage for bodily injury or death, so car repairs normally go through collision coverage. Check your policy for any add-on that covers property damage.
What if it was a hit-and-run?
Treat it like an uninsured driver: call the police right away, collect witness information and photos, and file the repair under your collision coverage. Our article on what to do when someone hits your parked car covers the first steps.
Will a claim for a crash I didn’t cause raise my rates?
It depends on your insurer and your policy. Ask your agent how they handle not-at-fault claims before you file.
Can I still choose my own body shop?
Yes. Arizona law gives you the right to choose any repair facility for your vehicle, whoever pays for the repair.
How long do I have to take action against the driver?
Arizona generally allows two years to bring a lawsuit for damage to property. Talk to an attorney for advice about your situation.
Get your car repaired in Tucson
If an uninsured driver hit your car, Formula 1 Collision Center can inspect the damage, write the estimate your insurer needs and handle the repair from start to finish. Call (520) 369-4291 or request an estimate.